Ever found yourself scratching your head wondering, “How much is auto insurance in Massachusetts?” You’re not alone! Navigating the world of auto insurance can feel like decoding an ancient language. But fear not, because we’re here to break it down into bite-sized, digestible nuggets.
Think of this guide as your personal GPS for the winding roads of Massachusetts auto insurance. We’re diving into everything from minimum coverage limits mandated by state law to sneaky ways to bring those premiums down. Buckle up, because we’re about to make you a savvy insurance shopper, Backlinko style!
Overview of Auto Insurance in Massachusetts
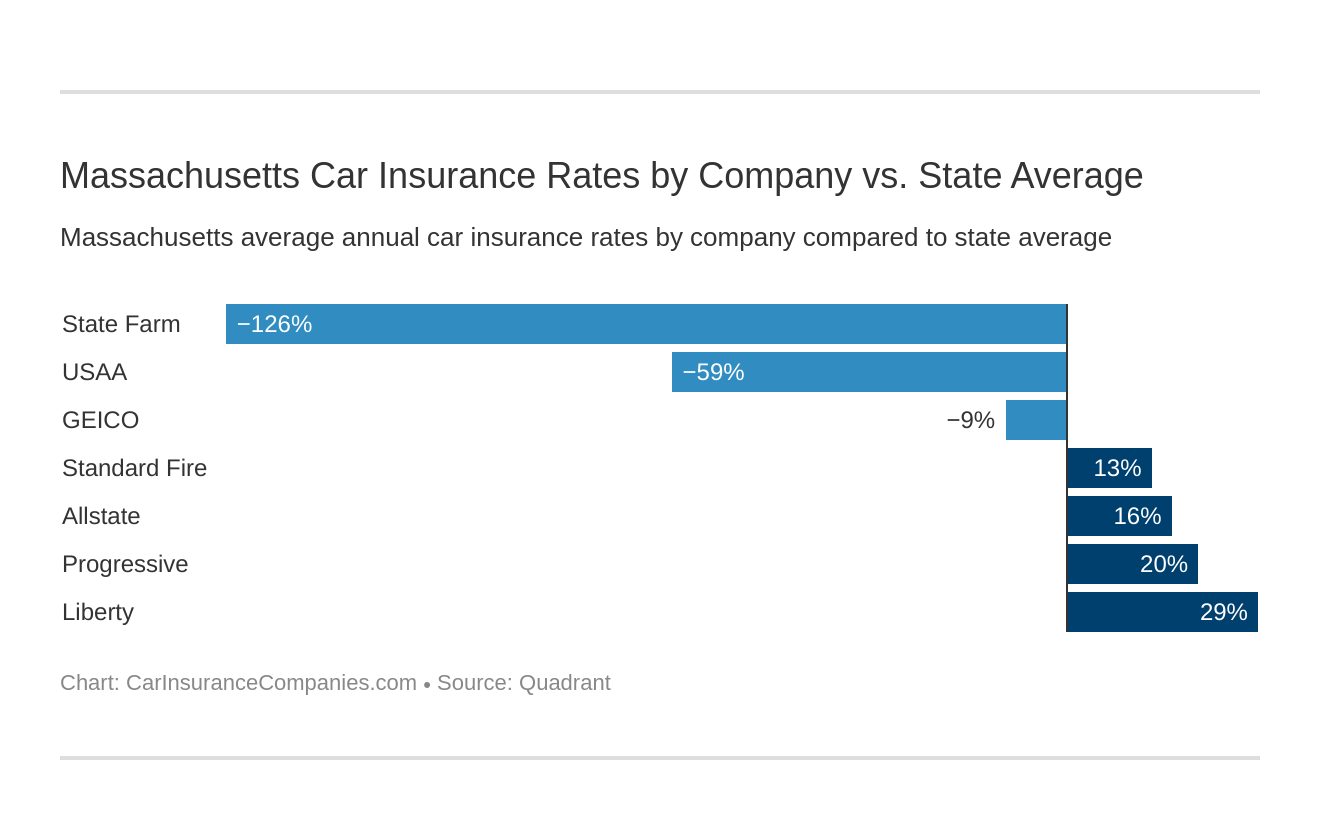
Did you know that Massachusetts is one of the few states with a no-fault auto insurance system? That means your insurance pays for your injuries regardless of who caused the accident.
Every car owner in Massachusetts must have car insurance. But there’s more to it than just signing up for a policy. You need to meet certain state-mandated coverage limits to legally drive your car.
Minimum Coverage Limits Required by State Law
In Massachusetts, the minimum coverage includes:
- $20,000 per person for bodily injury
- $40,000 per accident for bodily injury
- $5,000 for property damage
- $8,000 per person in personal injury protection (PIP)
Sounds like a lot? Well, it’s designed to keep you protected. BUT remember, these are just the state minimums.
How Massachusetts Regulations Impact Insurance Rates
Here’s the deal: Massachusetts has some unique regulations that can make insurance rates seem high. The state’s no-fault system and stringent requirements mean insurers take on more risk. This can lead to higher premiums.
Pro Tip: Shop around and compare quotes from different insurers. Don’t settle for the first quote you get.
For instance, factors like your driving history, where you live, and your vehicle’s value can significantly influence your premium.
Factors Influencing Auto Insurance Rates
Did you know that two people driving the same car in Massachusetts can pay wildly different rates for auto insurance? It’s true. These rates aren’t random; they’re influenced by a variety of factors.
Understanding what affects your premium can help you make informed decisions and potentially save money. Let’s dive into the key factors that can hike up your insurance costs.
Driving History’s Impact on Premiums
Your driving history is like your insurance report card. If you’ve had past accidents or violations, you’re likely paying more. Insurance companies see this as a risk and charge accordingly.
However, if you’ve maintained a clean driving record, you’re in luck. This can substantially lower your rates over time. But even a single traffic ticket can increase your premium by up to 22%. So drive safe!
Vehicle Type and Usage Matters
The type of car you drive and how you use it plays a major role in determining your insurance rates. Simply put, sports cars and luxury vehicles are more expensive to insure due to their higher repair costs and theft rates.
Furthermore, if you commute long distances daily, expect to pay more. Insurers assume that higher mileage increases your chances of accidents.
Other Key Influencing Factors
Beyond driving history and vehicle specifics, several personal factors affect your auto insurance premiums:
- Age: Younger drivers, especially teens, often face higher rates.
- Location: Urban areas with higher traffic and crime rates lead to higher premiums.
- Credit Score: A lower credit score can increase your insurance costs.
Pro Tip: Regularly checking and improving your credit score can lead to lower insurance premiums.
Average Cost of Auto Insurance
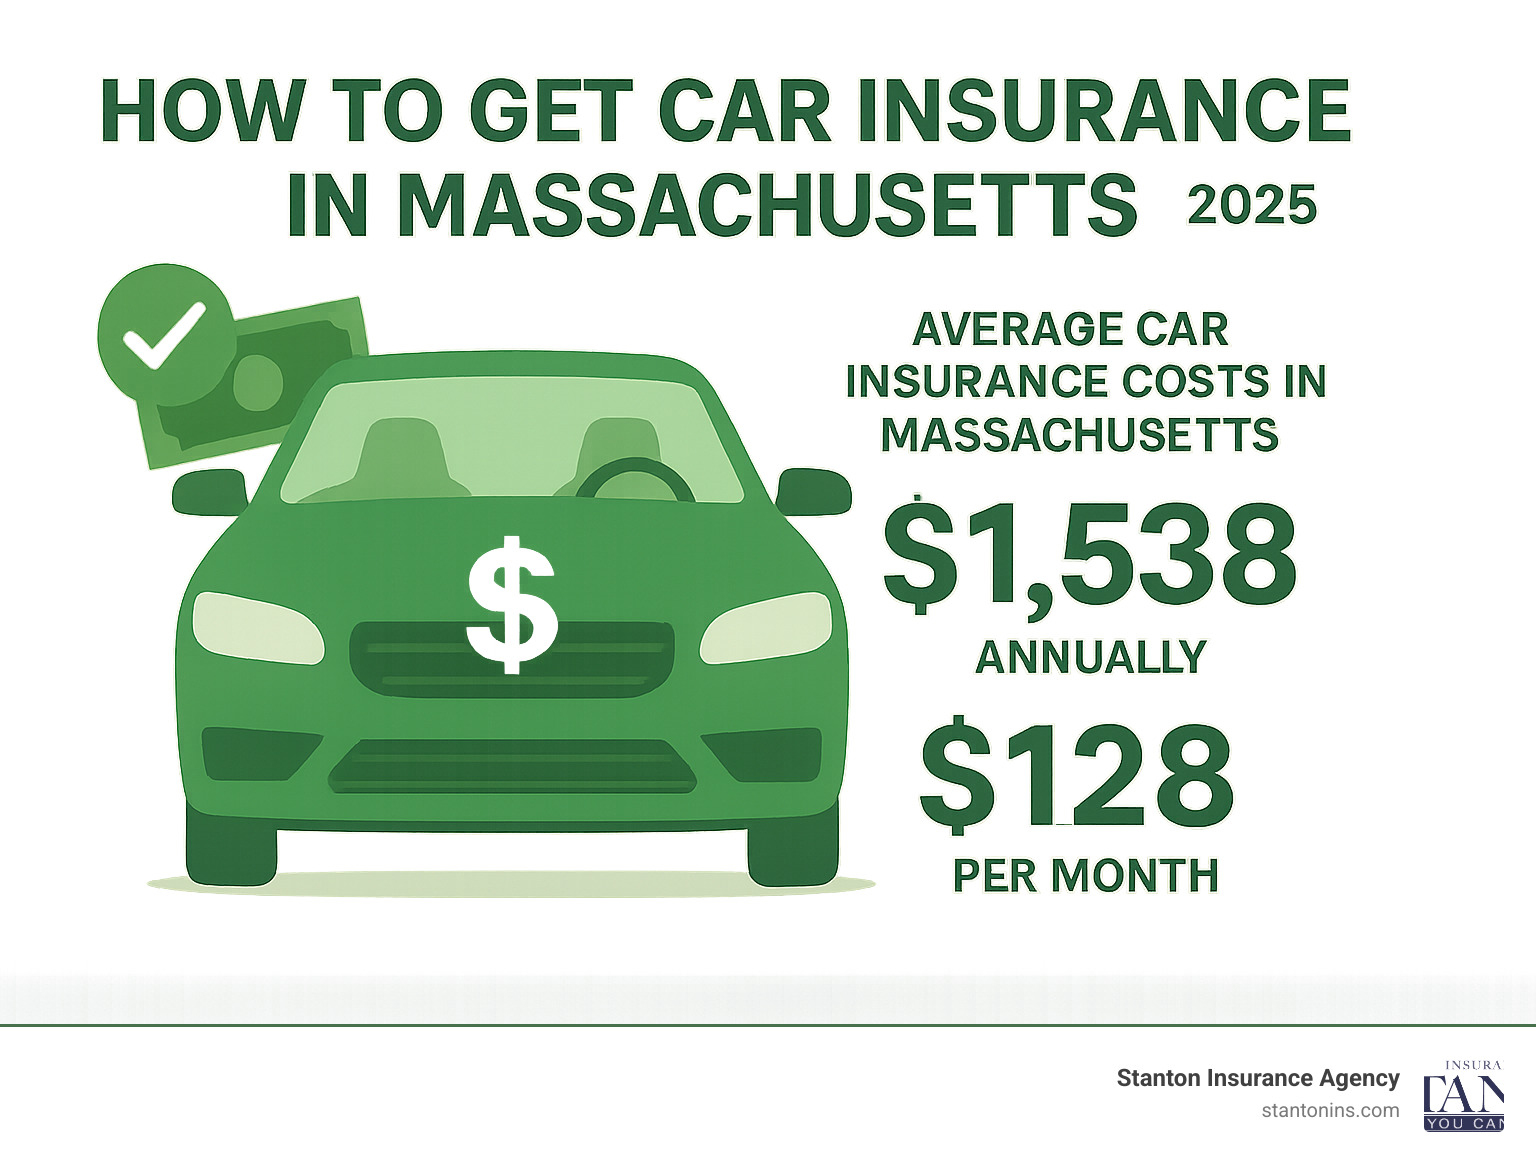
Want to know how much it costs to insure a car in Massachusetts? The average cost can vary dramatically depending on a few key factors. Let’s dive into the numbers and see what you might expect to pay.
Auto insurance rates in Massachusetts are influenced by factors like age, driving history, and even where you live. BUT what does the actual cost look like for different demographics across the state? Here is the deal: it’s all about the details.
Cost by Demographic and Coverage
Let’s break it down. Here’s a snapshot of average auto insurance costs in Massachusetts:
| Demographic | Basic Coverage | Full Coverage |
|---|---|---|
| Young Drivers (18-25) | $1,700 | $2,800 |
| Experienced Drivers (26-60) | $1,200 | $1,900 |
| Senior Drivers (61+) | $1,100 | $1,700 |
As you can see, younger drivers tend to pay much more. Why? Insurance companies see them as higher risk due to less driving experience.
City Comparisons
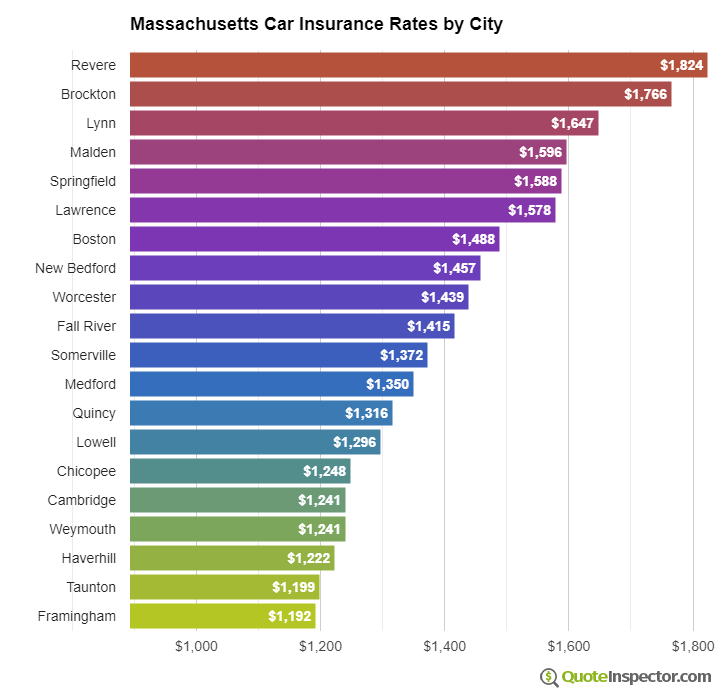
Where you live in Massachusetts can have a huge impact on your auto insurance rates. Check out these average costs:
| City | Average Cost |
|---|---|
| Boston | $2,200 |
| Worcester | $1,900 |
| Springfield | $1,800 |
Boston leads the pack with the highest rates, largely due to its dense traffic and higher accident rates. Location matters, folks!
Rate Trends Over the Years
Have you noticed your insurance premium creeping up? You are not alone. In Massachusetts, rates have been climbing steadily. Over the past five years, the average cost has increased by around 15%.
Why the rise? It’s a mix of factors including increased claims and repair costs.
Pro Tip: To combat rising rates, regularly shop around and compare quotes from different insurers.
Types of Coverage Options Available
Did you know that Massachusetts requires drivers to have a minimum level of auto insurance? But there’s a lot more to coverage than just meeting legal requirements. Let’s dive into the different types of auto insurance coverage available to you.
Auto insurance isn’t just about staying legal; it’s about safeguarding your financial future. Whether you’re new to Massachusetts or simply shopping around for better rates, understanding your coverage options is crucial. Here’s the deal: choosing the right type of coverage can save you a ton of money in the long run.
Understanding Comprehensive vs. Collision Coverage
Many drivers get confused about the difference between comprehensive and collision coverage. Comprehensive coverage steps in when your car is damaged by anything other than a collision—like theft or natural disasters. On the other hand, collision coverage is your best friend when you hit—or get hit by—another vehicle or object.
Pro Tip: If your car is older, you might want to reconsider collision coverage to save on premiums.
Coverage Types, Descriptions, and Benefits
It’s not just about comprehensive and collision. Let’s break down the main types of coverage you can choose from in Massachusetts:
| Coverage Type | Description | Benefits |
|---|---|---|
| Bodily Injury Liability | Covers injuries to others if you’re at fault. | Prevents personal financial loss due to lawsuits. |
| Property Damage Liability | Pays for damage to another person’s property. | Protections against costly property damage claims. |
| Personal Injury Protection (PIP) | Covers medical expenses regardless of who is at fault. | Essential for covering hospital bills and lost wages. |
| Uninsured/Underinsured Motorist | Protects you if the other driver doesn’t have insurance. | Ensures you’re not left paying out-of-pocket. |
Tips for Finding Affordable Auto Insurance
Are you tired of paying sky-high auto insurance premiums? You’re not alone. Many Massachusetts drivers find themselves shelling out more than they should for coverage.
The good news is, there are strategies you can use to bring those costs down. Let’s dig into some actionable tips you can start using today.
Strategic Ways to Reduce Premiums
One of the quickest ways to save on auto insurance is by shopping around. Rates can vary wildly between companies. Don’t just renew your current policy without checking what competitors offer.
Another tip is to raise your deductible. Yes, this means you’ll pay more out-of-pocket if you file a claim, but you’re likely to see a significant reduction in your monthly premium.
PRO TIP: Use a comparison tool to evaluate multiple quotes at once. You’ll save time and potentially hundreds of dollars.
Take Advantage of Common Discounts
Massachusetts insurers offer a variety of discounts that could save you big bucks. Are you a safe driver? You could qualify for a discount if you have a clean driving record.
- Good Student Discount: If you’re a student maintaining a B average or higher, you may be eligible.
- Multi-Car Discount: Insuring more than one car with the same company can lead to substantial savings.
- Low Mileage Discount: Drive less than 7,500 miles a year? You could pay less.
Always ask your insurance agent about discounts you might qualify for. It’s free money that many people overlook.
The Benefits of Bundling Insurance Policies
Here’s the deal: Bundling your auto insurance with other policies can lead to significant discounts. Consider combining your home, renters, or life insurance with the same provider.
Why is this effective? Insurance companies reward customers who bring more business their way. This translates into lower rates for you.
PRO TIP: Compare the bundled rate to individual policies to ensure you’re actually saving money.
Bundling isn’t just a marketing strategy; it’s a smart financial move that can simplify your insurance management and fatten your wallet.
Resources for Massachusetts Drivers
Are you overwhelmed by the endless choices for auto insurance? You’re not alone. Navigating the ins and outs of auto insurance in Massachusetts can feel like driving through a snowstorm.
Thankfully, there are excellent resources available to help guide you through the process. Whether you’re looking for government regulations or consumer guides, I’ve got you covered.
Essential Online Resources
Start with the Massachusetts Division of Insurance website. It’s a treasure trove of information on state regulations and consumer rights. Plus, they provide easy-to-understand guides for new drivers and seasoned pros alike.
- Massachusetts Division of Insurance – For official guidelines and policy updates.
- Find a Licensed Insurance Agent – Verify credentials before committing.
- Consumer Reports – Offers unbiased reviews and comparisons.
Mastering the Art of Comparing Insurance Quotes
Here’s the deal: comparing quotes is not just about price. Check the coverage limits, deductibles, and additional benefits. This way, you’ll know you’re getting the best bang for your buck.
- Use online comparison tools like Insurance.com.
- Calculate the potential savings vs. the coverage offered.
- Don’t forget to ask about discounts. You might qualify for more than you think.
How to File an Insurance Claim in Massachusetts
Pro Tip: Filing a claim? Always document the scene with photos and gather witness statements. This can strengthen your case significantly!
If you’ve been in an accident, don’t panic. First, ensure everyone’s safety and call the authorities. Once everyone’s safe, contact your insurance provider immediately to begin the claim process.
| Step | Action |
|---|---|
| Step #1 | Document every detail at the scene. |
| Step #2 | Notify your insurer with all gathered information. |
| Step #3 | Follow up regularly to ensure a quick resolution. |
Conclusion
Alright, road warriors of Massachusetts, you now have the ultimate roadmap to understanding auto insurance costs in your state. From the ins and outs of coverage options to sage advice on snagging the best rates, you’re equipped to hit the insurance highway with confidence. Remember, the key is to stay informed and proactive. Happy insuring!
Frequently Asked Questions
What are the basic requirements for auto insurance in Massachusetts?
Massachusetts requires drivers to have a minimum coverage of bodily injury and property damage liability, personal injury protection, and uninsured motorist coverage.
How does driving history affect auto insurance premiums?
Driving history is a significant factor; a clean record can lead to lower premiums, while accidents and violations usually result in higher rates.
Does the type of car I drive influence my insurance costs?
Yes, vehicle type and usage both play roles. Luxury or sports cars often come with higher premiums compared to standard vehicles.
Are there discounts available for Massachusetts drivers?
Absolutely! Common discounts include safe driver discounts, bundling policies, and discounts for vehicles with safety features.
How have auto insurance rates changed over the years in Massachusetts?
Rates can fluctuate based on market trends, claims history, and regulatory changes. It’s crucial to stay updated annually.
What resources are available for comparing insurance quotes in Massachusetts?
Utilize government websites, consumer guides, and online comparison tools to effectively evaluate different insurance offers.
How can I file an insurance claim in Massachusetts?
Begin by contacting your insurer immediately after an incident, provide necessary documentation, and follow their claim process for a swift resolution.
